Founders often ask me, “How much should we raise, and from whom?” The honest answer is: it depends on where you are. Startup fundraising happens in stages. Each stage asks you to prove something different, attracts a different kind of investor and unlocks a different amount of capital.
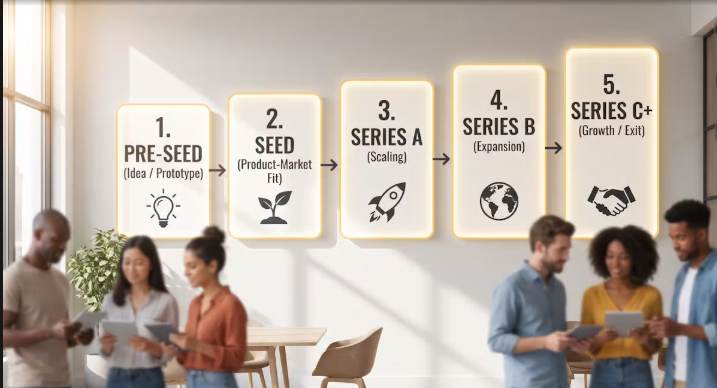
Here is how I explain the journey to the founders I work with.
1. Pre-Seed: the idea stage
What you are trying to do: Build the founding team, test the idea, do your market research and get a first version of the product (an MVP) in front of real people.
Who usually invests: You, your friends and family, angel investors, and a growing number of small funds that focus only on pre-seed.
At this stage money is usually raised through a SAFE (Simple Agreement for Future Equity) or a convertible note rather than by setting a share price. It keeps things simple while the business is still too early to value.
What investors want to see: A real problem worth solving, a team that can solve it, and a clear picture of how your product will do that.
2. Seed: proving people want it
What you are trying to do: Show product-market fit. You are finding out whether customers actually want what you built, improving the product, and winning your first active users or first revenue.
Who usually invests: Angel networks, seed-stage venture capital funds and, for some businesses, crowdfunding platforms.
Seed rounds can be priced rounds, where investors buy shares at an agreed value, or another round of SAFEs or convertible notes.
What investors want to see: Early traction: users who stay, a clear way to make money, and evidence that people are using the product, not just signing up.
3. Series A: building a repeatable business
What you are trying to do: You have a product that works and real traction. Now you need capital to build your go-to-market strategy, grow marketing and sales, and hire your first senior leaders.
Who usually invests: Institutional venture capital firms. One firm usually leads the round and sets the terms, and others join.
What investors want to see: Strong, consistent numbers: growing monthly or annual recurring revenue (MRR/ARR), low churn and healthy customer acquisition costs. Most of all, proof that your growth is repeatable and not a lucky streak.
4. Series B: expanding
What you are trying to do: Take a business that works and make it bigger: larger sales and marketing teams, new regions or countries, or new products that sit next to your core offering.
Who usually invests: Later-stage venture capital firms, growth equity funds and sometimes “crossover” investors who invest in both private and public companies.
What investors want to see: A strong position in your niche, unit economics that hold up as you scale, predictable revenue and a credible path to leading your market.
5. Series C and beyond: scaling up or preparing to exit
What you are trying to do: Grow at scale, expand globally, buy competitors, or get ready for an exit through a sale of the company or an initial public offering (IPO).
Who usually invests: Late-stage growth funds, private equity firms and, for some companies, hedge funds and other institutional investors. Investment banks usually come in as advisors on an acquisition or IPO rather than as investors.
What investors want to see: Market leadership, profitability or at least stable cash flow, and mature, audit-ready financial reporting.
The stages at a glance
| Stage | Main focus | Typical investors |
|---|---|---|
| Pre-Seed | Idea, team, MVP | Founders, friends and family, angels |
| Seed | Product-market fit, early traction | Angel networks, seed VCs |
| Series A | Scaling operations and go-to-market | Institutional VCs, with a lead investor |
| Series B | Market expansion | Growth equity and later-stage VC |
| Series C+ | Market leadership, acquisitions, pre-IPO | Late-stage growth funds, private equity, institutional investors |
A note for Canadian founders
Before you give away equity, look at the money you do not have to give shares for. Programs such as the NRC Industrial Research Assistance Program (IRAP) and the SR&ED tax credit can fund a meaningful part of your early research and development. Used well, they let you reach the next milestone, and a better valuation, with less dilution.
My take
Each round should buy you the proof you need for the next one. Raise too little and you run out of runway before you hit the milestone. Raise too much, too early, and you give away more of your company than you need to. Know which stage you are in, know what the next investor will want to see, and build your plan, and your numbers, around that.


Leave a Reply